
Business Line of Credit for Small Businesses Nationwide
From covering payroll to paying an invoice that’s due, Line of Credit LOC makes it simple. Get approved quickly, with no hidden fees and no nonsense — just a cycle that works: Withdraw. Repay. Repeat.
Line of Credit LOC Keeps Your Business Moving
Cover payroll, pay invoices, or seize new opportunities — all with a true line of credit.
Withdraw funds when needed, repay as you go, and repeat with no hidden fees. You only pay interest on what you draw.

Credit Line
up to
$275,000
Payment Terms
12-36 months

Payment Frequency
Weekly
or monthly
What is a business line of credit?
A Line of Credit LOC gives your business flexible access to funds whenever you need them. Draw from your credit limit and deposit funds directly into your business account — you only pay interest on what you use.
Like a business credit card, a revolving line of credit replenishes as you repay, so you can borrow again and again as your business grows.
It’s a smart way to manage cash flow, fund projects, and stay prepared for unexpected expenses or new opportunities. With Line of Credit LOC, working capital is always within reach.
Benefits of a Line of Credit.

Soft credit pull options
Many of our lending partners check eligibility with a soft credit pull, which doesn’t affect your credit score.
Fast funding
Once you’re approved, many of our lending partners can fund quickly, some as soon as the same day.
Build business credit history
Many of our lending partners report to business credit bureaus, so paying on time can help you build business credit.
How does a business line of credit work?
Unlike a traditional small business loan that gives you a lump sum upfront, a small business line of credit lets you borrow funds up to a set credit limit — so you can draw only what you need. As you repay your balance, your available credit replenishes, allowing you to keep borrowing without reapplying. Whether you’re managing cash flow or investing in growth, a revolving line of credit gives you flexible access to the funds your business needs.
A Line of Credit LOC can provide qualified businesses with credit limits up to $275,000. Once approved, you can draw funds as needed and pay interest only on what you use. If your lender reports to business credit bureaus, paying on time can also help build your business credit, giving your company even more opportunities to grow.
How do I apply for a business line of credit?
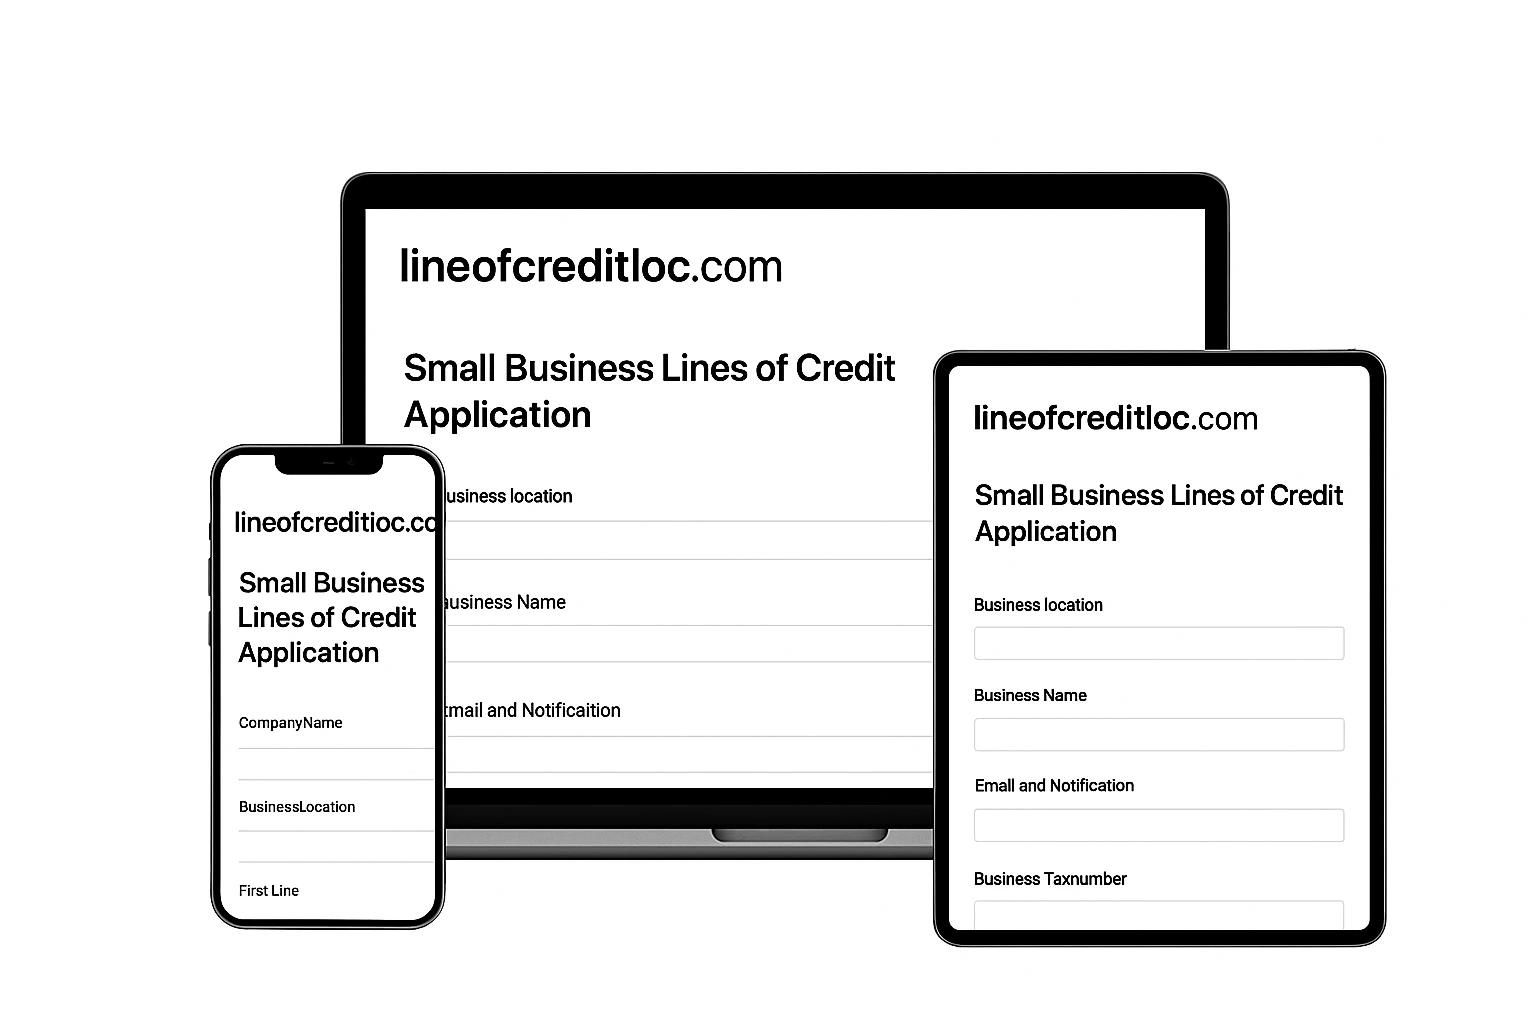
1
Complete the application.
Fill out one short online form with the basics about your business.
2
Get a decision.
We match you with lenders that offer revolving lines of credit, and a funding advisor helps you compare your options.
3
Receive your funds.
Pick the offer that fits, sign with the lender, and draw funds once you're approved, in some cases the same day.
Are we a match? Check our minimum requirements.
1 Year
In Business
Business
Checking Account
$50,000
Business Annual Revenue
625
Personal FICO* Score
FAQs: Business Line of Credit
What’s the difference between a business line of credit and a business term loan?
- Business line of credit. A line of credit gives you ongoing access to funds up to a set limit. You can take out money as needed and pay interest only on what you’ve drawn. As you make repayments, your available balance refreshes, making this option ideal for managing cash flow and covering recurring needs.
- Business term loan. A term loan provides a lump sum of cash upfront. You’ll pay interest on the full loan amount, with fixed repayment terms. This type of financing is often better suited for large, one-time expenses such as equipment purchases or real estate.
What’s the difference between a secured and unsecured business line of credit?
- Secured line of credit. Requires collateral, such as business assets, to secure the loan. These may offer lower rates but carry the risk of losing pledged assets if repayment terms aren’t met.
- Unsecured line of credit. Does not require collateral, though lenders may request a personal guarantee. These usually come with higher rates but protect business assets and can be more accessible for companies without significant collateral.
What’s the best line of credit for a small business?
What are the benefits of a business line of credit?
- Flexibility. Take money out only when your business needs it.
- Ready working capital. Use it for day-to-day bills, surprise expenses or a new opportunity.
- Lower cost. You pay interest only on the money you draw, not on your full limit.
- Steadier cash flow. Cover slow weeks so payroll and bills stay on schedule.
How much can I borrow with a business line of credit?
How do I repay a business line of credit?
How fast can I get funded?
How can I increase my credit limit?
How much does a line of credit cost?
Can I get a business line of credit without a credit check?
Can a line of credit help build business credit history?
What other funding options are available besides a line of credit?
- Term loans: Lump sum financing repaid over time.
- Equipment loans: Loans specifically for equipment purchases, often secured by the equipment itself.
- SBA loans: Government-backed loans with favorable terms but longer approval times.
- Microloans: Smaller loans, typically under $50,000, that may be easier to qualify for.